AI Infrastructure · Jonathan van den Berg · October 13, 2026
Meta Muse Wonder AI Models Reshape AI Data Center Power Demand and Critical Minerals Competition
Meta's release of Muse and Wonder multimodal models accelerates AI infrastructure buildout at a time when power grids and critical minerals supply chains are already strained, forcing investors to reassess exposure across data center operators, chipmakers, and sovereign capital allocators.
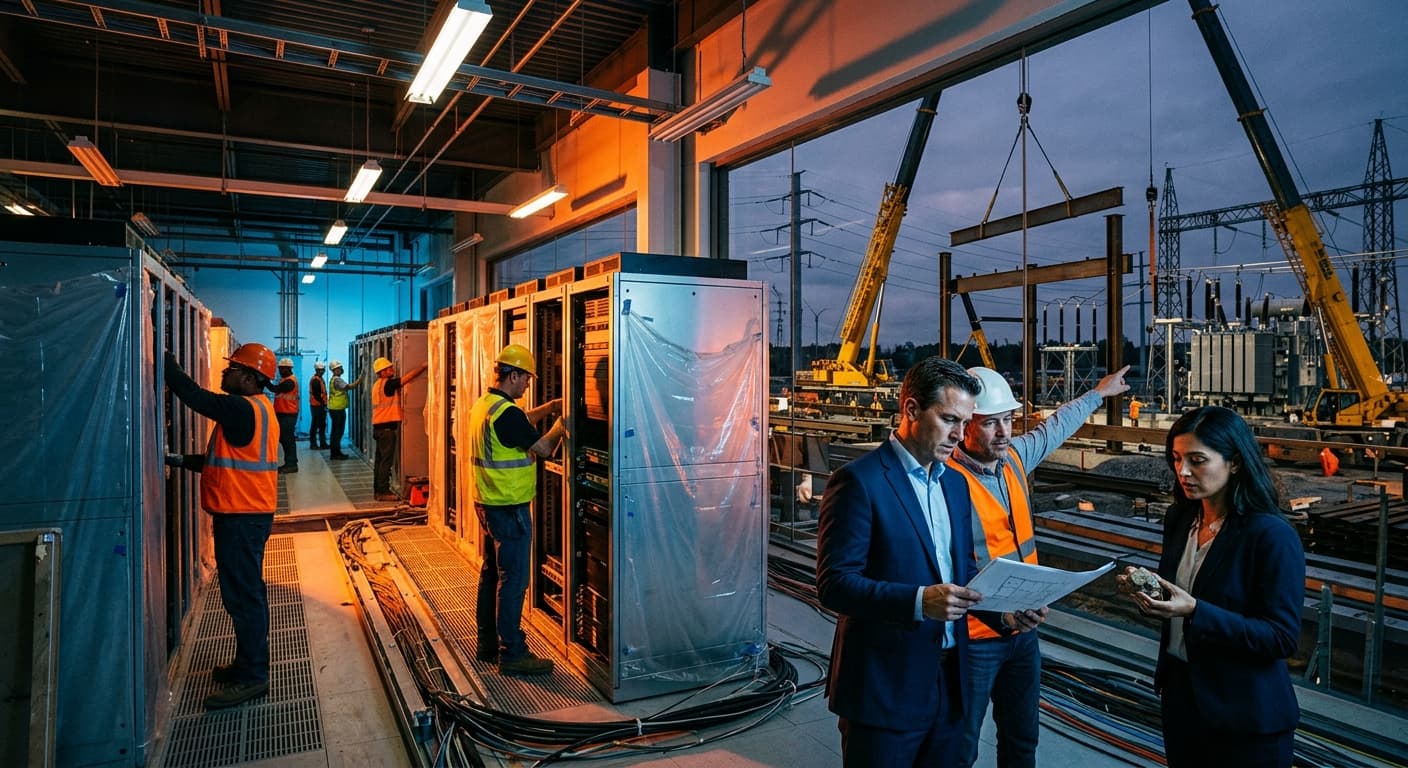
Meta's Muse and Wonder models push multimodal AI capabilities further into visual generation and agentic reasoning, driving fresh demand for GPU clusters and specialized inference hardware exactly when Northern Virginia data center operators face tightening power availability and critical minerals constraints are tightening globally.
Key Takeaways
- Meta's Muse Wonder models require dense clusters of high-bandwidth memory GPUs, increasing pressure on already constrained Northern Virginia power grids.
- Gallium, germanium, and rare earth elements used in advanced chips and data center infrastructure face heightened supply risk from export controls and chokepoints.
- Sovereign wealth funds are reallocating toward nuclear-powered data center sites and diversified mineral sourcing to hedge volatility.
- Chipmakers like TSMC, NVIDIA, and AMD see both upside from model training demand and downside from mineral shortages and sanctions exposure.
- Practical workarounds include on-site generation, advanced cooling, and accelerated permitting for small modular reactors near load centers.
What Meta Muse and Wonder Actually Deliver
Muse focuses on high-fidelity image and video synthesis from text prompts while Wonder emphasizes agentic workflows that combine reasoning with visual understanding. Both models demand significantly more compute per inference than earlier generations, particularly during fine-tuning and real-time interaction phases.
Early benchmarks shared by Meta show Wonder completing complex multi-step visual tasks 40% faster than previous in-house systems. That speed comes from larger context windows and denser transformer layers, which translate directly into higher power draw per query. For data center operators, this means sustained high utilization rates rather than the bursty loads seen in simple chat interfaces.
The launch arrives weeks after OpenAI revealed visual upgrades to its GPT series, setting up a clear competitive dynamic. Companies cannot afford to lag in multimodal capabilities if they want to retain developer mindshare and enterprise contracts.
Power Constraints in Major AI Hubs
Northern Virginia remains the world's largest data center market, yet available utility power has become scarce. Dominion Energy forecasts that AI-driven demand could consume an additional 5-7 gigawatts by 2030 in the region alone. Meta's new models accelerate that timeline.
Hyperscalers now compete directly with local utilities for capacity. Many are turning to power purchase agreements for renewable and nuclear output that bypass traditional grid queues. Yet even these deals face delays from supply chain bottlenecks on transformers and high-voltage equipment.
Small modular reactors (SMRs) have emerged as a favored long-term solution. Several tech firms have signed letters of intent with NuScale and other vendors, but regulatory approval and fuel supply remain years away. In the interim, operators rely on diesel backups and behind-the-meter gas turbines, both of which increase emissions and operating costs.
Vandenberg SpaceX launches have already highlighted how satellite-based power monitoring and rapid deployment of edge infrastructure can ease some pressure, yet core training clusters still require gigawatt-scale connections.
Critical Minerals Under Strain
Advanced AI chips rely heavily on gallium nitride and silicon carbide for power electronics, germanium for fiber optics, and rare earth elements for magnets in cooling systems. China controls roughly 80% of refined gallium and 60% of germanium processing. Recent export licensing requirements have created spot shortages and price spikes.
Lithium used in backup battery systems and cobalt in certain high-performance components also face pressure from competing electric vehicle demand. Nationalization moves in South American lithium districts add another layer of sovereign risk that fund managers must price in.
The intersection of these shortages with AI buildout creates a feedback loop. Higher mineral prices raise the cost of new chips and servers, which in turn slows data center expansion even as model complexity increases.
Modified NVIDIA GPUs with expanded VRAM illustrate the creativity operators use to stretch existing hardware, yet such workarounds cannot scale to meet Meta-scale training runs.
Sovereign Wealth Fund Reallocation Patterns
Funds in Abu Dhabi, Singapore, and Norway have quietly increased exposure to nuclear technology developers and critical minerals miners outside traditional supply chains. Temasek has added stakes in Australian rare earth projects while PIF has backed multiple SMR startups in the United States and Canada.
These moves reflect a broader shift from pure financial returns toward strategic resource security. Sovereign capital now competes with venture and private equity for projects that secure long-term power and mineral offtake agreements.
Allocations to traditional hyperscaler equity remain large, but with added hedges through direct infrastructure investments. This dual approach reduces portfolio volatility when commodity prices swing on geopolitical news.
Ukraine-related supply disruptions earlier demonstrated how quickly mineral flows can shift, teaching sovereign investors to maintain diversified holdings across multiple jurisdictions.
Competitive Landscape and Chipmaker Exposure
| Company | Ticker | Key Exposure | Risk Factor |
|---|---|---|---|
| Meta Platforms | NASDAQ:META | Model developer and large-scale deployer | Power and mineral cost inflation |
| NVIDIA | NASDAQ:NVDA | GPU market leader for training | Supply chain chokepoints on HBM and advanced packaging |
| AMD | NASDAQ:AMD | Growing inference share | Competition for limited wafer capacity at TSMC |
| TSMC | NYSE:TSM | Foundry for AI accelerators | Geopolitical risk in Taiwan and mineral import reliance |
| Oracle | NYSE:ORCL | Cloud and data center operator | Northern Virginia grid constraints |
Oracle's cloud expansion in particular has positioned it as an alternative to pure hyperscalers for enterprises seeking managed AI capacity. Its stock reaction to Meta's announcement reflected investor belief that third-party providers will capture overflow demand that internal clusters cannot meet due to power limits.
Common Mistakes Investors Make
- Assuming all AI demand translates into linear revenue growth for chipmakers without modeling power and mineral bottlenecks.
- Overlooking secondary sanctions risks on entities involved in critical minerals processing in sanctioned jurisdictions.
- Treating data center real estate as a simple yield play rather than a strategic infrastructure asset tied to national energy policy.
- Failing to differentiate between training and inference workloads when estimating power consumption per model generation.
Best Practices for Portfolio Positioning
- Build positions in companies with secured power offtake agreements or direct access to nuclear capacity.
- Diversify critical minerals exposure across Australia, Canada, and emerging African producers rather than relying on dominant Asian processors.
- Monitor regulatory changes around data center permitting and grid interconnection queues as closely as model benchmark releases.
- Use options or structured products to hedge against sudden commodity price spikes triggered by export restrictions.
- Evaluate sovereign wealth fund flow data as a leading indicator for long-term infrastructure investment trends.
How Chokepoints Amplify Volatility
The Malacca Strait, Bab el-Mandeb, and Strait of Hormuz remain vital for energy and component shipments feeding Asian foundries and Western data centers. Any disruption quickly appears in spot prices for both oil and specialty gases used in chip fabrication.
Recent Houthi activity near Bab el-Mandeb has already prompted shipping lines to reroute, adding days and cost to semiconductor logistics. Combined with mineral export controls, these maritime risks create compounded pressure on AI supply chains.
FAQ
How much additional power will Meta's Muse and Wonder models require?
Exact figures are not public, but industry estimates suggest a 25-35% increase in inference power density compared with previous multimodal systems when deployed at scale. Training runs for future versions could push single-cluster demand beyond 100 megawatts.
Which critical minerals face the tightest supply for AI infrastructure?
Gallium, germanium, and high-purity quartz used in crucibles for silicon wafer production currently show the highest supply risk. Neodymium for magnets in liquid cooling pumps is also constrained.
Are sovereign wealth funds exiting traditional tech stocks?
No. They are supplementing equity holdings with direct investments in power generation, mineral mining, and data center real estate to create vertically integrated exposure.
What role does Northern Virginia play in the broader AI ecosystem?
It hosts more than 70% of global internet traffic at peak times and remains the preferred location for low-latency East Coast serving. Power shortages there force some workloads to secondary markets like Texas or the Midwest.
Can new interface designs like those in GPT-6 reduce power needs?
Visual and agentic interfaces tend to increase overall compute because they require additional modalities and longer context. Efficiency gains in one area are often offset by richer user experiences.
Conclusion
Meta's Muse and Wonder models represent another step-function increase in AI capability that the current infrastructure can barely support. Investors who map power availability, mineral flows, and sovereign capital patterns together will hold clearer insight than those chasing headline benchmark scores alone. The winners over the next cycle will be those who secure energy and materials before the next round of model releases begins. Anthropic's warning on self-replicating AI models
Review your exposure to data center operators, chip foundries, and critical minerals producers with these constraints in mind. Positions built on realistic power and resource assumptions will outperform those based on unconstrained growth narratives.
Sources
Share This Article